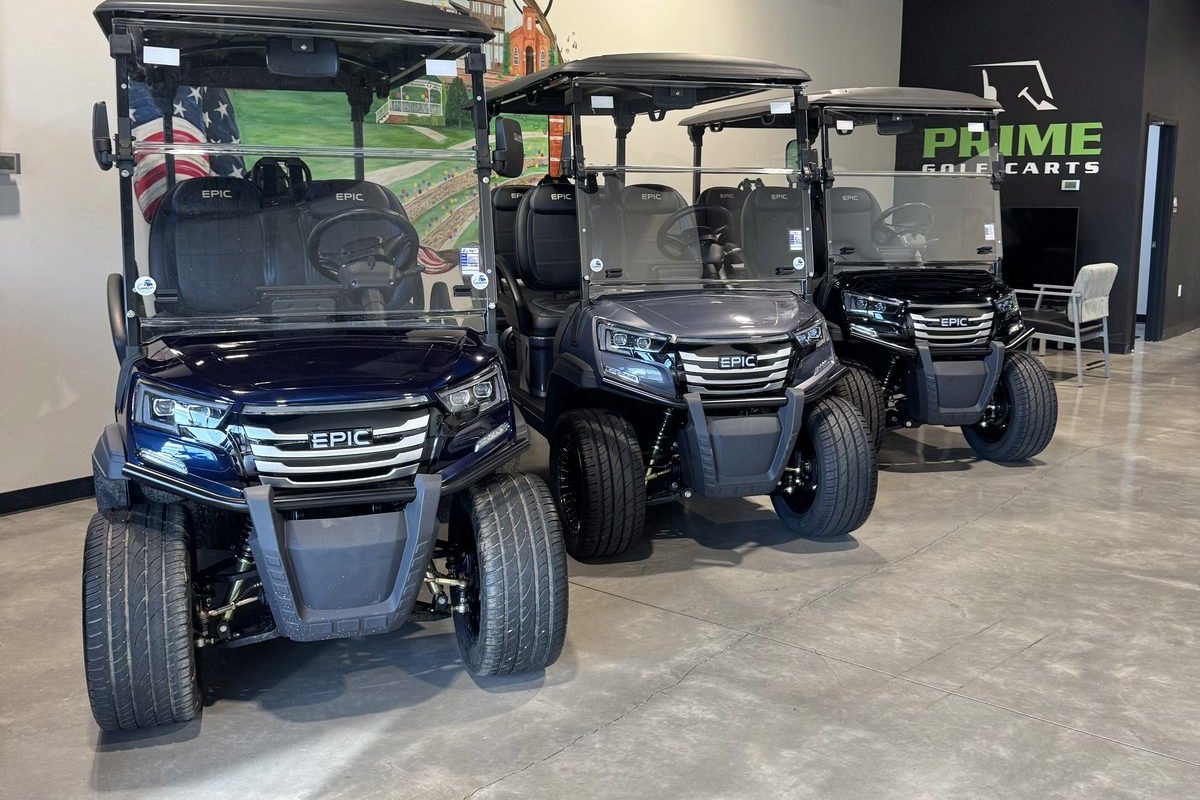
Golf carts have moved well beyond the fairway. In Cherokee County and the Woodstock area, carts are showing up in neighborhoods, on greenways, and at job sites — and most people who want one aren't planning to pay cash. new carts on our lot run from about $9,000 for a basic model to just under $17,000 for a fully equipped street-legal build, and used carts start near $4,000 (see current inventory), so financing has become the standard way most buyers get into a cart. Here's what the financing process actually looks like, and what to expect at Prime Golf Carts of Woodstock.
Why People Finance Golf Carts
The same logic that applies to financing a car applies to a cart. Spreading a $9,000–$14,000 purchase across 48–60 months keeps monthly payments manageable while you hold on to cash. Golf carts also hold their value reasonably well compared to many recreational products — a well-maintained, name-brand electric cart depreciates slowly, which makes financing less painful than it is for, say, an ATV.
Financing also lets buyers step up to a better model than they might otherwise consider. The difference between a base cart and a street-legal, lifted, lithium-battery build with custom upholstery might be $4,000–$5,000 — a meaningful number in cash, but a modest difference in a monthly payment.
What Golf Cart Financing Typically Looks Like
Golf cart loans function similarly to recreational vehicle or powersports loans. Terms commonly run from two to six years, and your rate depends on your credit profile, the lender, and whether the cart is new or used. For scale, the most recent figure in the Federal Reserve’s G.19 consumer credit release puts the average 60-month new-car loan at commercial banks at 7.14%; cart loans generally price at or above that. Buyers with strong credit often qualify for promotional rates. Buyers with challenged credit still have options, though at higher rates — and a larger down payment helps offset that.
Most lenders categorize golf carts as recreational vehicles or personal property loans rather than auto loans, which means the process is slightly different from buying a car. You typically don't need to title a standard (non-street-legal) cart the way you would a vehicle.
Street-Legal Carts and Auto Financing
Street-legal carts — those built to Low Speed Vehicle (LSV) standards with a VIN, headlights, turn signals, seat belts, and mirrors — are a slightly different financing category. Because they're registered vehicles, some lenders will underwrite them as auto loans, which often means better rates and longer terms than a personal property loan.
Georgia treats two things differently here. A golf cart driven on local streets posted at 35 mph or less needs no state registration or license plate. A low-speed vehicle (LSV) is a separate, federally regulated classification that must be titled and registered with the Georgia Department of Revenue’s Motor Vehicle Division. That distinction can matter for financing, because a titled LSV is sometimes eligible for more traditional auto-loan channels. We cover the difference in detail in our guide to street-legal golf carts in Woodstock — worth raising when you go through the financing process.
What Affects Your Golf Cart Loan Rate?
The same factors that affect any consumer loan apply here:
- Credit score — the primary driver of your rate tier.
- Down payment — 10–20% down is typical; a larger down payment reduces both the loan amount and the perceived lender risk.
- Loan term — longer terms lower the monthly payment but increase total interest paid.
- Cart type and age — new carts from established brands are easier to finance than older or custom units.
How to Finance a Golf Cart at Prime Golf Carts of Woodstock
We work with lenders who specialize in recreational and small vehicle financing. When you're ready, the process is straightforward:
- Pick the cart you want — or let us help you identify the right model for your needs and budget.
- Fill out a credit application. It takes about 10 minutes and we typically get a decision quickly.
- Review the loan terms and choose the option that fits your monthly budget.
- Sign and take your cart home.
We can run financing scenarios for you before you apply so you know what to expect. There's no obligation and no impact to your credit for an initial estimate.
Tips for Getting the Best Rate
Check your credit report before you apply — errors are common and can be disputed. If your score is lower than you'd like, a larger down payment often makes a meaningful difference in the rate you're offered. Shopping timing also matters: promotional financing offers from manufacturers sometimes appear around model-year changeovers and major holidays.
Frequently Asked Questions
Can I finance a used golf cart?
Yes, though lenders have more requirements for used carts — typically related to age and condition. Financing is generally easier on newer (less than 3–5 years old) carts from major brands. We carry both new and quality pre-owned inventory; let us know your budget and we'll work within it.
What credit score do I need to finance a golf cart?
There's no universal minimum, and different lenders have different thresholds. As a rule of thumb the strongest rate tiers open up in the 700s; scores in the mid-600s and below usually mean a higher rate rather than a decline, and financing is often still possible with a larger down payment or a co-signer.
How much should I expect to put down?
10–20% is typical. On a $10,000 cart, that's $1,000–$2,000 down. Some lenders will approve zero-down for strong credit profiles, and some promotions include low-interest or deferred-interest terms with no money down.
Does financing a golf cart affect my auto insurance?
Standard golf carts are typically covered under a homeowner's or renter's policy (with limits) or a dedicated cart/recreational vehicle policy. Street-legal LSVs usually require their own vehicle insurance policy. The lender may require proof of insurance on financed carts.
Can I pay off my golf cart loan early?
Most golf cart loans don't carry prepayment penalties, but it's worth confirming with the lender before you sign. Paying extra on the principal each month reduces your total interest cost even if you don't pay it off in full early.
Ready to get into a cart? Contact Prime Golf Carts of Woodstock to start the financing process or to talk through which model fits your budget — we're at (470) 349-0381.